What to Know Before Buying Commercial Property on the Mississippi Gulf Coast
What to Know Before Buying Commercial Property on the Mississippi Gulf Coast
Nov 4, 2026 · @Philip Demoran
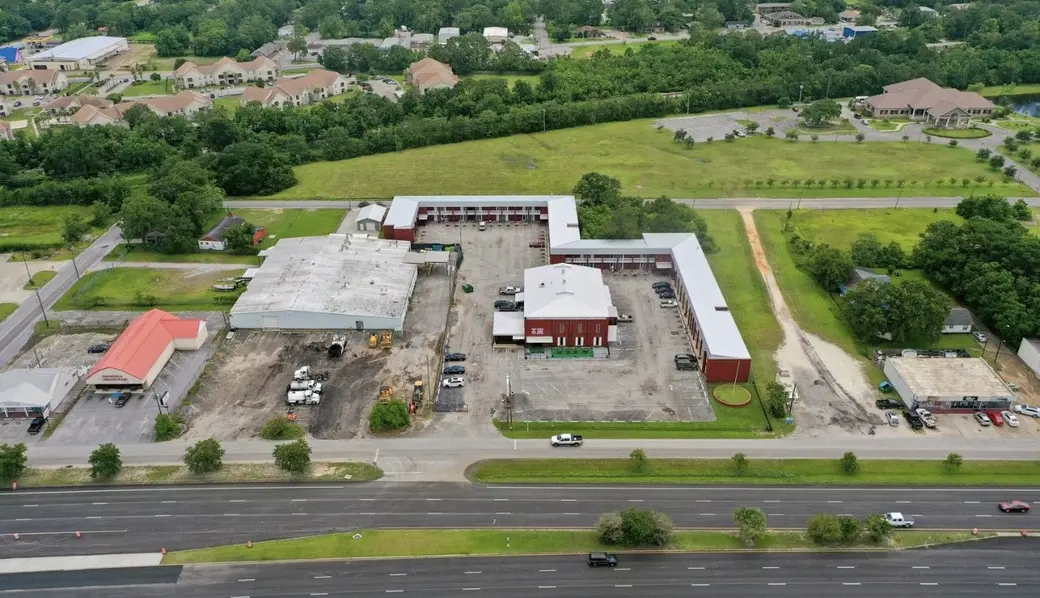
Buying commercial property on the Mississippi Gulf Coast can be a smart move, but the Coast has its own rules. Flood maps, the state wind pool, city-by-city zoning, and a sale-price system most out-of-state buyers have never seen can all change what a property is really worth to you.
Whether you're eyeing a retail building in Gulfport, a warehouse near the Port of Pascagoula, or a lot on a busy corridor in D'Iberville or Ocean Springs, here's what to know before you sign a contract.
1. Start with the flood zone, not the floor plan
On the Coast, a property's FEMA flood zone can matter as much as its location. It affects your insurance cost, what your lender requires, and what you're allowed to build or renovate.
- Pull the flood zone early. FEMA's Flood Map Service Center shows whether a parcel sits in a high-risk zone (A, AE, or V/VE) or a lower-risk one (X).
- Ask for an elevation certificate. It shows how high the building sits relative to the base flood elevation, which drives flood premiums. If the seller doesn't have one, a surveyor can produce it.
- Watch the substantial improvement rule. In a high-risk zone, if renovations cost 50% or more of the building's value, the whole structure may have to be brought up to current elevation standards. That can turn a "light remodel" into a major project.
- Look at the site, too. Drainage, storm surge history, and how the property did in past storms tell you things a map can't.
2. Get insurance quotes before you're under contract
Insurance is often the number that makes or breaks a Coast deal. A property that looks like a bargain can stop penciling out once you see the premiums.
Commercial owners here usually need three separate pieces of coverage:
- Property coverage from a standard carrier, which in the coastal counties often excludes or limits wind and hail.
- Wind and hail coverage, either from a private or surplus-lines carrier or from the Mississippi Windstorm Underwriting Association (MWUA). The MWUA is the state's insurer of last resort for wind and hail in the six southernmost counties: Hancock, Harrison, Jackson, Pearl River, Stone, and George. It covers wind and hail only, and commercial terms differ from residential.
- Flood coverage, through the National Flood Insurance Program or a private flood carrier.
Ask a local commercial insurance agent for quotes during your inspection period, and ask the seller for their current premiums and loss history. Build realistic insurance numbers into your budget or your cap rate math from day one.
3. Confirm zoning with the right local office
The Coast is a patchwork of cities and unincorporated county land, and each has its own zoning code. A use that's allowed in Gulfport may need a variance in Biloxi, and a parcel just outside city limits may fall under county rules instead.
Before you buy, confirm with the city or county planning department:
- That your intended use is permitted by right, not just "close enough"
- Parking, signage, setback, and landscaping requirements
- Any overlay districts, such as historic, waterfront, or corridor overlays
- Whether the current building and use are legally nonconforming, and what happens if you expand or change tenants
If you need a rezoning or special use permit, make your contract contingent on getting it.
4. Don't shortcut due diligence
Commercial deals don't come with the same buyer protections as a home purchase. Your inspection period is where you find problems, so use all of it.
- Phase I Environmental Site Assessment. Most lenders require one, and it's worth doing even with cash. Former gas stations, auto shops, dry cleaners, and industrial sites carry real cleanup risk.
- An ALTA survey shows boundaries, easements, encroachments, and access. On the Coast, it should also confirm the flood zone.
- Look for easements, liens, deed restrictions, and access issues before closing.
- Building inspections. Roof, HVAC, electrical, plumbing, and structure. Ask specifically about storm damage and past repairs.
- Leases and financials. For income property, review every lease, rent roll, and the last two to three years of operating statements. Get tenant estoppel certificates before closing.
5. Know that sale prices aren't public here
Mississippi is a non-disclosure state: closed sale prices are not part of the public record. You can't simply look up what the building next door sold for, and online value estimates for commercial property are often far off.
That makes local market knowledge especially valuable. A broker who closes commercial deals on the Coast can pull MLS data, draw on recent transactions, and tell you what comparable properties actually traded for.
For income-producing property, value comes from the numbers. Look at net operating income, cap rate, tenant quality, and lease terms, and stress-test them with realistic insurance and tax figures. A higher cap rate on the Coast may simply reflect higher insurance costs.
6. Budget for commercial property taxes
Mississippi taxes property by class. A single-family, owner-occupied home is assessed at 10% of true value, but commercial and other non-homestead real property is assessed at 15%. The local millage rate is then applied to that assessed value, and rates vary by city, county, and school district.
Here's how it works on a $500,000 commercial building, using a 125-mill rate as an example:
|
Step |
Amount |
|
True value |
$500,000 |
|
Assessed value (15%) |
$75,000 |
|
Annual tax at 125 mills |
$9,375 |
Check the actual millage with the county tax collector, and don't assume the seller's current tax bill will carry over after a sale. Also ask about local and state incentives. Depending on the location and project, some businesses may qualify for tax exemptions or other programs, so talk with the city, county economic development office, or your CPA early.
7. Understand what drives demand on the Coast
The best commercial buys line up with what keeps the local economy moving. On the Mississippi Gulf Coast, that includes:
- Shipbuilding and industry in Jackson County, anchored by Pascagoula's shipyards and the Port of Pascagoula
- Military at Keesler Air Force Base in Biloxi and the Naval Construction Battalion Center in Gulfport
- Gaming and tourism along the Biloxi and Gulfport waterfront, which supports hospitality, restaurants, and retail
- Port and logistics activity at the Port of Gulfport, which drives demand for warehouse and industrial space
- Population growth in communities like Ocean Springs, D'Iberville, and north Harrison County, which supports medical office, service retail, and daily-needs centers
Ask who your future tenants or customers are, and whether they'll still be there in five or ten years.
Quick checklist before you make an offer
- ☐ Flood zone and elevation certificate reviewed
- ☐ Wind, flood, and property insurance quotes in hand
- ☐ Zoning and intended use confirmed with the city or county
- ☐ Phase I environmental, survey, and title ordered
- ☐ Building inspected, including storm repair history
- ☐ Leases, rent roll, and operating statements reviewed
- ☐ Property tax estimated at the 15% commercial assessment
- ☐ Comparable sales reviewed with a local commercial broker
Work with a broker who knows Coast commercial real estate
The Demoran Realty Group helps buyers find, evaluate, and close on commercial property across the Mississippi Gulf Coast, with a focus on Harrison and Jackson counties. From the first site visit through closing, we'll help you see the real costs and opportunities before you commit.
Ready to talk about your next commercial property? Call us at 228-382-0455 or visit demoranrealtygroup.com to get started.
This article is general information, not legal, tax, or insurance advice. Talk with the appropriate professionals about your specific situation.
Sources
Recent Posts


"My job is to find and attract mastery-based agents to the office, protect the culture, and make sure everyone is happy! "
13524 Seymour Ave., Ocean Springs, MS 39564, United States